Lockheed’s $58.62 Billion PAC-3 Ceiling Is a Demand Signal, Not Cash in the Bank
War.gov and Lockheed put a $58.62 billion multiyear face value on PAC-3 MSE—but no funds were obligated at award. Here’s how investors should read the ceiling.
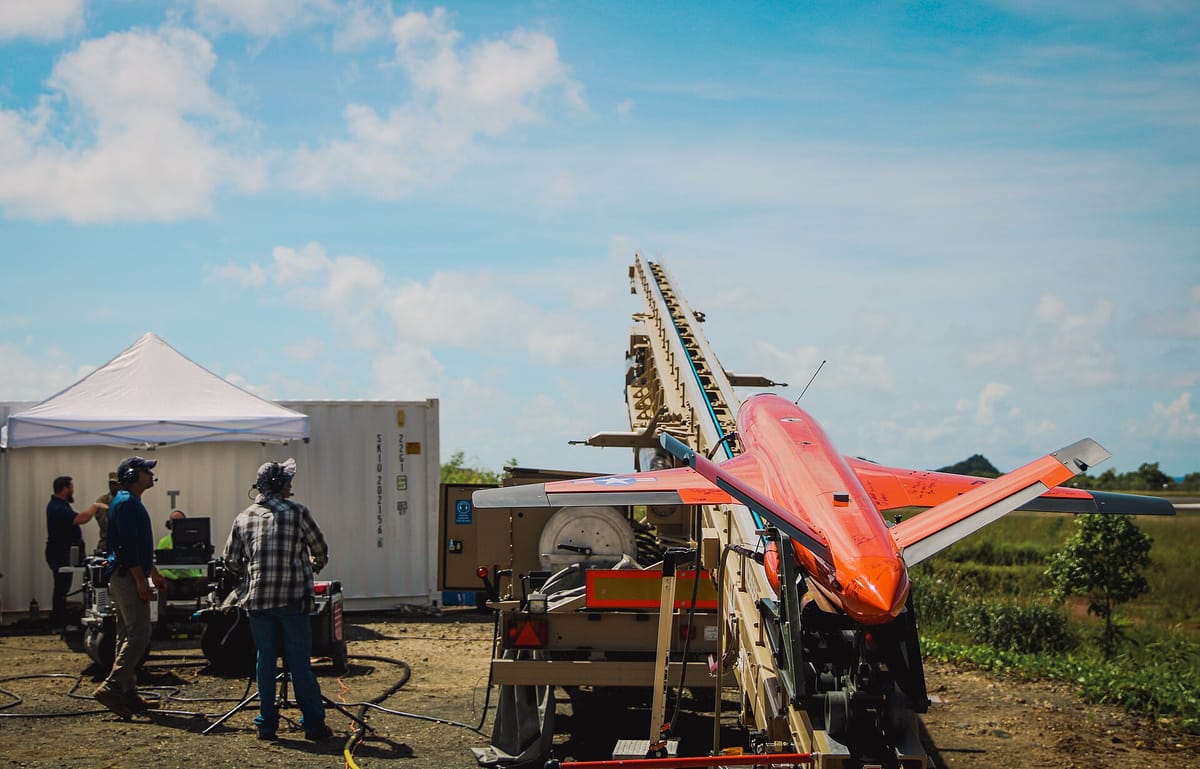
For investors parsing Lockheed Martin’s (NYSE: LMT) latest Patriot headline, the number that travels farthest—$58.62 billion—is also the easiest to misread. It is a multiyear ceiling and a demand signal, not cash booked, not revenue recognized, and not a check cleared on award day.
On July 29, 2026, the U.S. government awarded Lockheed Martin a seven-year undefinitized contract action (UCA) modification for up to $53.86 billion for PAC-3 Missile Segment Enhancement (MSE) interceptors, according to the company’s July 29 release. That modification sits on top of a $4.7 billion year-one UCA from April, bringing the cumulative multiyear contract face value to $58.62 billion. The Department of War’s July 30 contracts announcement records the same arithmetic in official form: a $53,859,843,289 firm-fixed-price modification (P00002) to contract W31P4Q-26-C-0013, lifting cumulative face value to $58,620,843,289, with estimated completion March 31, 2035—and no funds obligated at the time of award.
What the War.gov notice actually says
The Army Contracting Command at Redstone Arsenal framed P00002 as converting the current one-year UCA into a seven-year multiyear procurement structure, increasing the not-to-exceed ceiling and encompassing hardware, equipment, and manufacturing efforts required to produce PAC-3 MSE missiles. Places of performance stretch across the industrial base—from Grand Prairie and Lufkin, Texas, and Camden, Arkansas, to Rocket Center, West Virginia, Clearwater and other Florida sites, and more than a dozen locations listed in the contracts bulletin.
That geographic footprint matters because it maps the choke points: seekers, motors, structures, and final all-up round assembly. Lockheed’s release emphasizes Camden as the home of final all-up round production and says the award supports a 50% increase in jobs there—from 1,200 to approximately 1,850—while enabling the company to “triple capacity by the end of 2030.” Those are Lockheed’s stated targets, not Department of War quantity tables; the War.gov notice does not disclose interceptor unit counts for this modification.
Secondary coverage sometimes collapses the award into a simple “$58.62 billion PAC-3 contract.” The primary sources are more precise. Lockheed describes a seven-year UCA modification for up to $53.86 billion that, with the prior $4.7 billion year-one UCA, totals $58.62 billion. War.gov lists the modification value to the dollar and the cumulative face value to the dollar. Neither document turns the ceiling into a firm quantity buy on day one.
Ceiling versus cash: the investor distinction
Three mechanics keep this headline from being “revenue today.” First, it is still described by Lockheed as a UCA modification—terms, prices, and quantities remain subject to definitization. Second, War.gov is explicit that no funds were obligated at award; funding arrives later through appropriations and order action. Third, a not-to-exceed cumulative face value is an authorization envelope, not a sales booking under ASC 606. Investors who confuse ceiling with backlog, or backlog with near-term cash, will mis-model both free cash flow and working-capital intensity through the late 2020s.
Lockheed’s release also situates the PAC-3 action inside the Department of War’s Acquisition Transformation Strategy and notes that this is the company’s second major multiyear munitions contract under that model, following a separate $35 billion THAAD acceleration contract. Those are related industrial-policy stories—but they are not the same award. Mixing the PAC-3 ceiling with the THAAD figure is a common secondary-source error; the primary documents keep them apart.
The Department’s own framing, reflected in Under Secretary of War for Acquisition and Sustainment Michael P. Duffey’s quote in Lockheed’s release, is about demand signals: giving industry the long-term visibility required to hire, tool, and buy materials. That is an acquisition-strategy story as much as a Lockheed story. For the stock, the investable question is how quickly the envelope converts into funded orders and how much capital Lockheed must deploy ahead of that conversion.
What Lockheed says it will spend to deliver
Demand signals only work if suppliers believe them enough to put capital at risk. Lockheed says it is investing $8 to $9 billion through 2030 to modernize more than 20 U.S. facilities and scale munitions output, citing groundbreakings this year at the Munitions Production Center Building 47 in Troy, Alabama (supporting THAAD and future Next-Generation Interceptor work) and the Munitions Acceleration Center in Camden, Arkansas (supporting PAC-3), per the company release.
Chairman, President and CEO Jim Taiclet called the moment “once-in-a-generation,” tying investment, hiring, and facility upgrades to the government’s acquisition transformation. Operational color in the release—PAC-3 MSE’s role in recent real-world defense missions—explains why allied and U.S. demand has been “soaring,” in Lockheed’s words. It does not, by itself, prove the timing of cash collections against the $58.62 billion face value.
Questions the street should ask next
For equity analysts, the useful follow-ups are operational, not theatrical. When will the UCA be definitized, and what share of the $58.62 billion ceiling becomes firm priced quantity? How much of the envelope is U.S. Army missile procurement versus Foreign Military Sales? How will Camden and Troy capital spending translate into quarterly CapEx and margin timing as production ramps toward Lockheed’s stated 2030 capacity goal? And how do second-source motor agreements elsewhere in the supply chain—announced in the same policy wave—change Lockheed’s own supplier risk and unit-cost trajectory?
None of those answers live inside a single contracts notice. What the July 29–30 paper trail does establish is narrower and more investable: the Department of War has raised the PAC-3 MSE multiyear not-to-exceed ceiling to $58,620,843,289 on W31P4Q-26-C-0013 via a $53,859,843,289 firm-fixed-price modification, completion is dated through March 31, 2035, and no money moved on award day. Treat $58.62 billion as the size of the demand signal—not as cash in the bank.